I. Shanghai
Shanghai is a city of commerce without apology.
Money is made, exchanged, counted and reinvested. The towers, banks, shopping streets and endless movement of goods carry the same message: this is a city that understands trade.
It has also quietly emerged as the world’s biggest physical gold exchange.
Walking through Shanghai, a principle from monetary history kept returning to me.
Gresham’s Law.
Bad money drives out good.
Under a gold standard, take two instruments, each denominated at one pound: a paper banknote and a gold sovereign. The sovereign contains the gold. The banknote promises its equivalent. The denomination is the same. The backing is not.
When both must be accepted at the same nominal value, the doubtful banknote is spent and the sovereign retained. The paper circulates. The gold goes into reserve. Its owner understands the difference between a pound printed on a promise and a pound settled in gold.
Shanghai gives that distinction physical form. Paper claims move across screens while gold is weighed, tested, bought and stored. One can be created by extending a balance sheet. The other must be acquired.
I was born in 1971, the year the United States closed the gold window. The dollar’s remaining convertibility into gold was suspended. The suspension was called temporary. It became the new order.
I later entered the relationship market believing men and women still exchanged hard currencies. Restraint and exclusivity would meet loyalty and commitment. I would build my reserves. The woman would preserve hers. Both would bring something scarce to the settlement.
I had little capital and little success. I worked, built a career, accumulated money, bought a house and established a company. Female interest increased. The timing was the evidence.
My personality had not suddenly appeared. What had changed was the backing.
I had become hard currency.
Meanwhile, women had been issuing another currency. Sexual access circulated without the commitment I was still accumulating the means to provide. Other men received it on terms never offered to me.
I remained on the old standard while the new currency circulated elsewhere.
One market. Two instruments. Different exchange rates.
II. Hard Currency
The inherited bargain rested on reciprocal scarcity.
But the starting balance sheets were different.
The man began with an empty vault. The woman began with the gold already in hers.
His task was accumulation. Hers was preservation.
The female currency was femininity, purity, sexual restraint and selectivity, with exclusivity promised at settlement. The male currency was accumulated competence, capital and stability, with courtship, loyalty, provision and permanence promised at settlement. He built the reserves he would offer. She preserved the reserves with which she entered the market. The bargain joined acquired reserves to preserved reserves.
A man spends years building his side of the settlement.
Competence requires practice. Capital requires earnings, restraint and accumulation. Stability requires decisions repeated long after their novelty has disappeared. A reputation for reliability requires a record. The house, the savings and the capacity to provide represent life already expended.
Commitment then adds a claim on life still to come.
A man who commits allocates future time, income, attention and optionality. He accepts obligations that may outlast the attraction which brought him into the arrangement. His offer is backed by both accumulated reserves and future production.
That currency is expensive to manufacture.
Demand does not cheapen that currency or create a claim upon it.
The female reserve was the scarcity and selectivity attached to sexual access. It was not manufactured through years of earnings. It was present at the beginning, and its preservation determined what remained available for the eventual settlement.
Cheap issuance did not add gold to that vault. It spent the scarcity which had given the original promise its value. More paper could circulate while less backing remained behind the denomination.
The old bargain made sense while both vaults could support the exchange. Being chosen for an exclusive settlement meant something when access had not already circulated on easier terms.
The sexual revolution broke that reciprocity.
It did not abolish the old denomination. It introduced a cheaper instrument beside it, then continued demanding settlement at the old price.
III. The Second Currency
The new currency allowed sexual issuance to multiply without a corresponding increase in reserves.
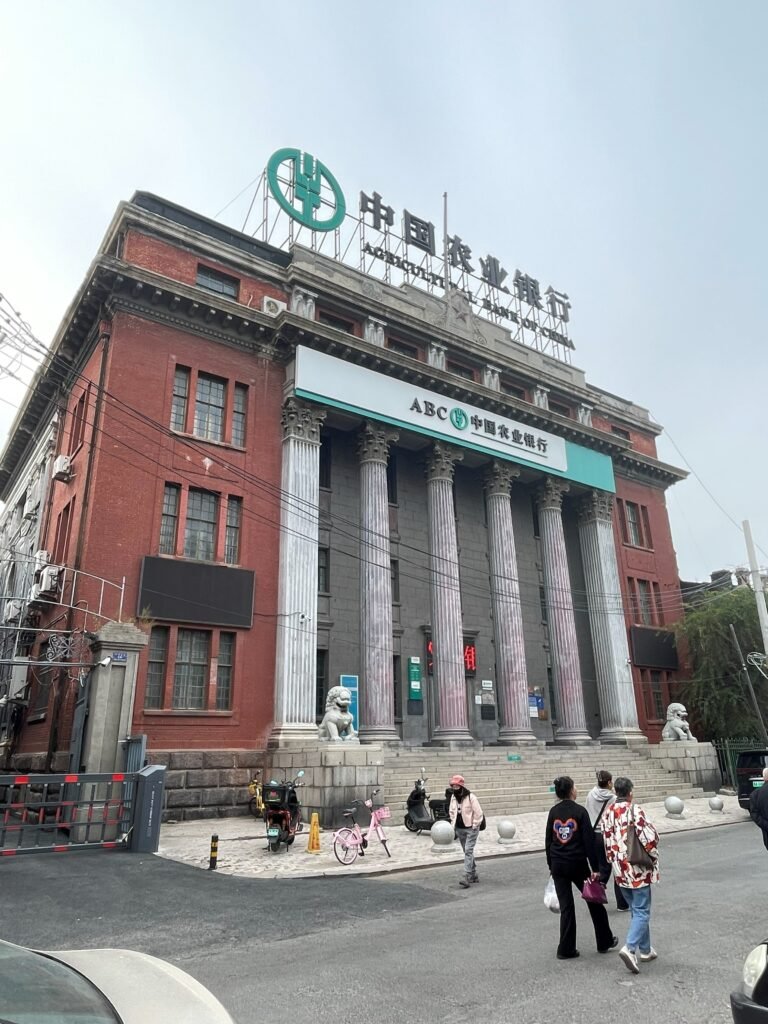
Traditional courtship had pillars: family, church, community, reputation and ceremony. Those institutions imposed friction, kept records and made issuance visible. Modern dating demolished the temple and handed every woman a private printing press. Circulation became opaque. Reserves could not be audited. The ledger became self-reported. Yet every note still arrived marked scarce, exclusive and premium-grade. Every dating profile might as well have stood between two Corinthian columns with an issuing clerk behind the desk.
Hookups, casual sex and situationships allowed sexual access to circulate without courtship, exclusivity or a credible future. Contraception and abortion weakened the connection between sex and childbirth. Feminism recast restraint as repression and judgement as illegitimate, reducing the reputational cost of issuance.
Digital platforms widened the market. Anonymous foreign holidays removed the local ledger: no shared social circle, no lasting reputation and a departure date built into the transaction. A woman could issue freely abroad, return to the man whose commitment remained in place and seal the foreign episode inside a separate compartment. He continued pricing the relationship without knowing a second ledger even existed.
What had required a substantial commitment could be issued for immediate desire.
But increased supply did not mean equal access.
Women directed the new currency toward the men they desired most. Highly desired men obtained it without supplying the old backing. They did not need to offer a house, provision, patient courtship or marriage to receive what other men were still accumulating commitment to obtain.
Men outside that flow continued accumulating. They worked, established themselves and prepared for a relationship market whose advertised terms still required serious commitment.
They encountered scarcity while supply expanded elsewhere.
This was the central asymmetry. The same market could be liquid for one class of men and expensive for another. The men receiving cheap issuance had little reason to buy the old bundle. The men expected to buy the old bundle had received little of the cheap issuance.
They were not the beneficiaries of the inflation.
They became its later counterparties.
The two instruments circulated inside the same market, while feminist doctrine insisted that the exchange rate had never changed.
IV. The Hidden Ledger
Choosing a bank requires more than admiring its frontage.
The building may look solid. Its name may inspire confidence. The banknote may carry a handsome promise to pay one pound. None of that establishes how much gold remains in the vault or how many paper claims have been issued against it.
The question is not whether the note looks respectable. It is whether the bank can support the settlement it promises.
The same examination belongs in the relationship market. A man who has spent years filling his own vault needs to know whether the institution offering him a note has preserved its reserves, or merely continued printing against an old reputation for solidity.
Every bank has an issuance history.
A printed denomination does not establish backing. Nor does the declaration of present exclusivity erase the terms on which access was previously offered.
The ledger records selectivity, volume, recipients and price. Who received access? What did they contribute? How readily was it offered? What is now being demanded from the man approached for permanence?
Extensive prior sexual availability reduces a woman’s long-term relationship value in the male market. The proposition is worth less because the scarcity and selectivity men value have already been reduced. Calling the history irrelevant does not restore them.
Volume matters. Terms matter. Exchange rates matter.
A man who received access through desire alone and a man later asked for resources, legal commitment and years of loyalty were offered different prices. The later offer cannot be valued by its label alone.
Present exclusivity is part of the offer. Its history is part of the valuation.
Concealment adds duplicity, but concealment does not create the dilution. The issuance has already occurred. Hiding the ledger merely prevents the next counterparty from pricing it accurately.
Nor does a higher asking price establish a higher value. A demand for permanence reveals what the issuer wants. It does not demonstrate what the buyer will receive.
The banknote says one pound.
The vault determines what that promise is worth.
V. Slagflation
The expansion of sexual currency created a powerful arbitrage.
Women issued cheaply to men selected for immediate desire, then sought permanent settlement from other men in the old denomination: courtship, resources, protection, loyalty and marriage.
One market supplied excitement. The other supplied backing. The advantage lay in taking the benefits of both while denying that the first transaction changed the value of the second.
This is slagflation.
Slagflation is the inflation of female sexual issuance combined with continued demand for premium male settlement.
The consequence was delayed, not abolished. Issuance and settlement had simply been separated by a decade or more.
The new currency expanded while the advertised cost of male commitment remained high. Sexual access became easier to issue. The years required to build a solvent, competent and reliable man did not become easier to compress.
Women observed what other women obtained and adjusted their behaviour. What began as an individual advantage became a market norm. Feminist doctrine then supplied its moral justification: female issuance was private and irrelevant, while male resources, intentions and future commitment remained open to inspection, negotiation and judgement.
The asymmetry entered the accounting itself. One ledger was examinable. The other was supposed to be accepted unopened.
The trade cleared while men still honoured the inherited bargain.
Men continued accumulating against the inherited bargain and failed to audit the market. They assumed that the currency offered to them had been preserved under a discipline resembling their own. Their assets were real. Their understanding of the exchange rate was obsolete.
They had mistaken scarcity to themselves for scarcity in the market. The earlier price had been low. The later price was high. A generation of men had kept accumulating against terms that no longer existed.
Women had circulated paper and requested settlement in gold.
The arbitrage depended on the later man accepting the denomination without examining the issuance. Once he compared the two, the difference could no longer be hidden inside the language of commitment.
VI. The Repricing
No arbitrage survives discovery forever.
Men began comparing exchange rates. They distinguished being desired from being selected to provide. They noticed when substantial obligations were being demanded for an offer previously made without them.
Why release years of accumulated capital and a claim on future life at the historic price when the reciprocal scarcity had already been diluted?
Repricing followed.
Some men offered less courtship, less provision and less commitment. Others extended the audit, watching behaviour before releasing reserves. Some accepted casual terms while refusing permanent liabilities. Others stopped trading.
The responses differed. The effect was the same: hard currency became harder to obtain.
Feminist orthodoxy continued treating the one-pound banknote and the one-pound sovereign as though matching denominations guaranteed equal backing. Men who recognised the difference began retaining their gold rather than exchanging it for paper of uncertain redemption value.
Their competence had not disappeared. Their capital had not vanished. Their capacity for loyalty had not ceased to exist. Those reserves were withheld from transactions that failed to justify their release.
Once men withheld their half, the old reciprocal bargain could no longer circulate on demand.
Women who still wanted the old settlement called this male commitment phobia.
The market has no commitment phobia. It has a bid.
This was a valuation crisis.
The asking price remained high because women still wanted the old benefits. The bid fell because the buyer no longer accepted the old valuation. Calling him reluctant, immature or afraid of commitment did not close the spread.
Nor could additional accumulation solve it. A larger reserve does not improve the terms of a bad exchange. It merely gives the holder more to surrender.
The good money withdrew because its owners could finally see what they were being asked to buy.
VII. Into Reserve
Shanghai understands the distinction.
Paper moves quickly. Credit expands. Numbers multiply across screens. Physical gold must be weighed, tested, acquired and settled.
Its absence from ordinary circulation does not mean it has lost its value. It means its holders understand its value and refuse the offered exchange rate.
The same logic applies to accumulated male capital.
A man who has built resources, competence, stability and the capacity to commit holds assets with uses beyond the relationship market. They can finance movement, experience, independence and a life already worth living. Their value does not depend on surrendering them to someone else’s preferred settlement.
Commitment is available when the return justifies the allocation. Its mere availability creates no claim upon it.
I read the ledger. I examine the issuing bank, its reserves and its history. I distinguish a well-backed promise from a demand that my own gold should make good someone else’s paper.
When the exchange rate is false, I retain my gold.
Bad money has driven out good.
Hard currency will return when the settlement is again backed on both sides.